
Southeast Asia Unites for Faster Cross-Border Money Transfers
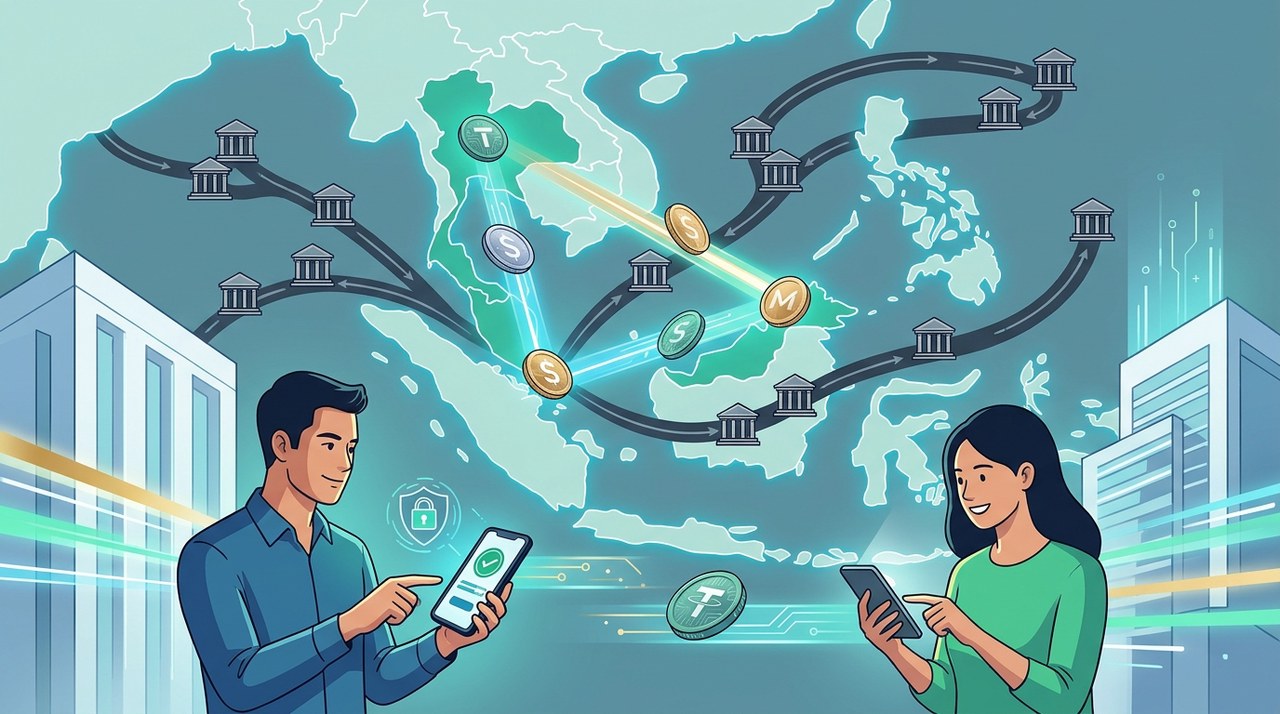
What is Happening with Project BLOOM?
If you have ever tried sending money to a friend or business partner in another country, you know that international bank transfers can be slow and expensive. Traditional cross-border payments often pass through multiple financial institutions, each charging fees and adding delays.
A major initiative in Southeast Asia aims to change that reality. Malaysia and Thailand have officially joined Singapore in a collaborative effort known as Project BLOOM. This initiative focuses on helping financial institutions coordinate the cross-border use of stablecoins and tokenized bank deposits to dramatically cut transaction costs and speed up transfer times.
Why Traditional Cross-Border Payments Are Costly
To understand why Project BLOOM is so significant, it helps to look at how international money transfers work right now. When you send money from one country to another using traditional bank channels, the money rarely moves directly from Bank A to Bank B.
Instead, the payment travels through a network of middleman institutions called correspondent banks. Each bank along the route checks the transfer, processes compliance checks, and takes a small cut of the funds as a processing fee. Additionally, foreign exchange rate markups can further erode the final amount received.
This multi-step path leads to several key friction points for consumers and businesses alike:
- High processing fees layered across multiple intermediary banks
- Settlement delays ranging from a few hours to several business days
- Lack of real-time visibility into transaction status
- Operational downtime during weekends and public holidays
Understanding the Tools: Stablecoins vs Tokenized Deposits
Project BLOOM centers around two specific digital financial assets: stablecoins and tokenized commercial bank deposits. While both run on modern digital ledgers, they serve slightly different roles in the financial ecosystem.
What is a Stablecoin?
A stablecoin is a digital token designed to maintain a stable value by linking its price to a conventional currency, such as the US Dollar, Singapore Dollar, or Thai Baht. Unlike volatile cryptocurrencies, stablecoins aim to provide price stability, making them useful for daily payments and settlement on blockchain networks.
What is a Tokenized Deposit?
A tokenized deposit represents traditional commercial bank money recorded on a secure, distributed ledger. When a customer holds funds at a regulated bank, the bank creates a digital token that corresponds directly to those existing cash deposits.
Because tokenized deposits remain tied to regulated commercial banks, they give institutions a familiar, highly compliant vehicle for settling transactions digitally across borders.
How Project BLOOM Aims to Lower Costs
Project BLOOM works by establishing shared technical protocols and regulatory alignment between participating nations. Instead of sending money through several correspondent institutions, participating banks in Singapore, Malaysia, and Thailand can interact directly on interoperable digital platforms.
By enabling direct tokenized settlements, financial institutions can eliminate middleman charges and complete transfers almost instantly, 24 hours a day and 7 days a week.
Project BLOOM aims to streamline cross-border finance by replacing multi-layered correspondent banking channels with direct digital settlement systems.
Why Southeast Asia is Leading Digital Currency Initiatives
Southeast Asia is one of the world's fastest-growing digital economies. Regional trade between ASEAN nations is heavy, and millions of workers rely on cross-border remittances to send money home to their families.
Central banks and financial regulators in Singapore, Malaysia, and Thailand have long recognized that reducing payment friction directly supports regional economic growth. By working together on initiatives like BLOOM, these nations are building a unified framework for the future of Asian finance.
Key Benefits and Risks to Keep in Mind
While cross-border digital settlement brings substantial potential advantages, it also requires careful risk management from financial regulators and participating banks.
Potential Advantages
- Reduced costs for international commercial transactions and individual remittances
- Near-instantaneous payment settlement around the clock
- Enhanced transaction transparency on shared digital networks
- Greater financial inclusion and support for cross-border trade
Operational Considerations and Risks
- Regulatory alignment across different national legal frameworks requires ongoing oversight
- Technical systems and smart contracts must maintain robust security against potential cyberCYBER+0.00% threats
- Liquidity management must be sustained to prevent currency conversion slippage during volatile market conditions
It is important for readers to remember that digital assets and financial innovations carry operational and market risks. Past performance of digital assets or financial institutions is not a guarantee of future performance. For live market information and historical data, you can visit Bitkub Market.
The Path Ahead for Cross-Border Finance
The addition of Malaysia and Thailand to Singapore's Project BLOOM marks an exciting step toward unified digital finance in Southeast Asia. As testing continues, this regional collaboration could provide a blueprint for how countries around the globe modernize international payment systems.
Latest blog posts


 +2
XRP Expert Explains How Network Usage Impacts Token Value
XRPL validator Vet debunks popular myths about XRP's utility, auto-bridging, and why real-world ledger adoption matters for long-term value.
|

Bitcoin ETFs Face $635M Outflows as October Turns Red
Thursday's $635 million ETF withdrawals snapped a three-day streak, pushing October into $175 million in net outflows.
|


Soft Underwater Robot Swims in 3D with Just Two Actuators
NC State researchers created a soft underwater robot inspired by feather stars that maneuvers in 3D using only two pneumatic actuators.
|