
SoFi Launches Tokenized Deposit with 4.40% APY
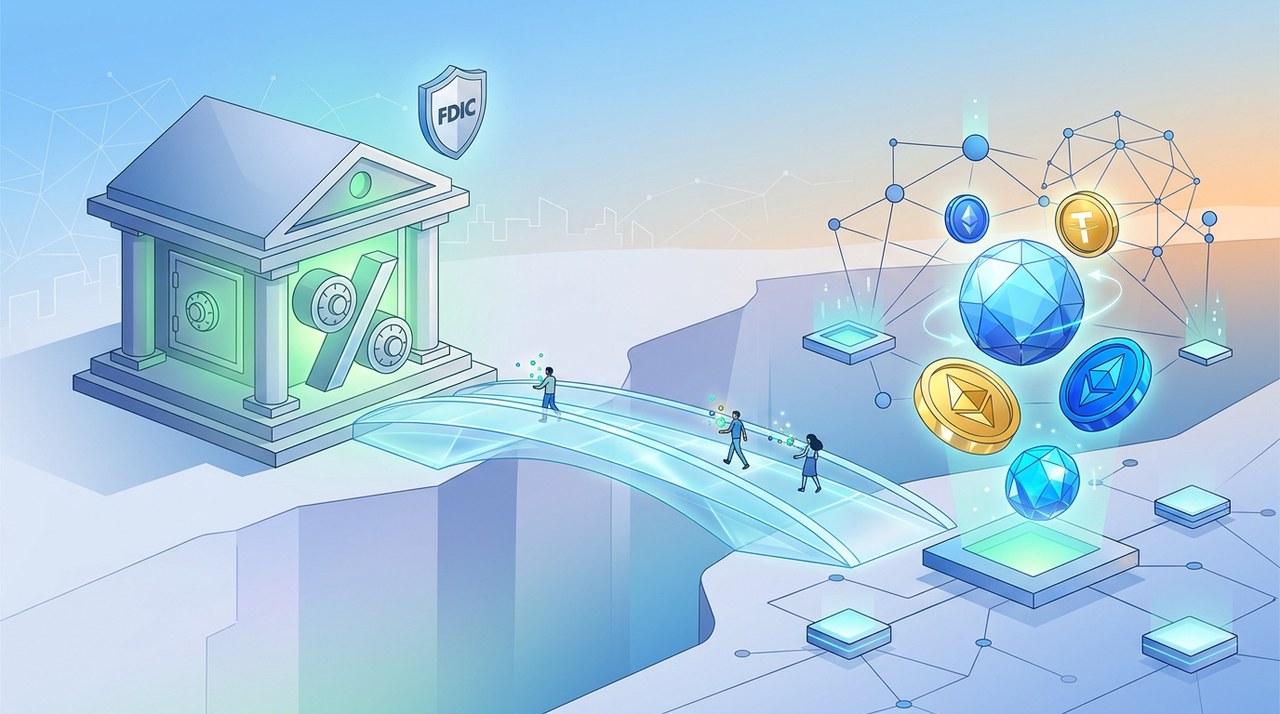
A New Bridge Between Banking and Crypto
Traditional banking and the fast-moving world of cryptocurrency are coming closer together. SoFi Bank recently launched SoFi Earn, a new tokenized deposit account designed specifically for yield-bearing crypto funds and institutional users.
This product gives users a 4.40% Annual Percentage Yield (APY) while maintaining standard FDIC insurance coverage. Additionally, it allows depositors to seamlessly convert their funds into stablecoins at any time, 24 hours a day, 7 days a week.
By launching SoFi Earn, the regulated bank aims to help digital asset funds earn steady interest on cash reserves while remaining fully connected to liquidity in the crypto market.
What Is a Tokenized Deposit?
To understand why this launch is significant, it helps to break down what a tokenized deposit actually is. Think of a standard bank deposit as money stored securely inside a regulated vault. Normally, you can only interact with that money using standard banking apps, wire transfers, or debit cards during normal banking hours.
A tokenized deposit creates a digital representation—or token—of that exact bank balance on a blockchain ledger. It acts like a digital claim ticket for your cash.
Because the token lives on a distributed ledger, it can be moved or converted instantly at any time. However, because it represents an actual deposit at a licensed financial institution, it keeps the traditional protections of a regular bank account.
Key Features of SoFi Earn
SoFi Earn brings together several key features that appeal to institutional treasury teams and crypto fund managers:
1. 4.40% APY Yield
Cash reserves held in the account earn a yield of 4.40% APY. This allows funds to generate competitive returns on their idle cash reserves without having to take on higher-risk yield strategies.
2. FDIC Insurance Coverage
Unlike standard crypto assets or unbacked stablecoins, funds held within SoFi Earn carry FDIC insurance up to applicable legal limits. This provides institutional investors with familiar consumer and business protections.
3. 24/7 Conversion to Stablecoins
Crypto markets never close, but traditional wire transfers usually stop operating on weekends and holidays. SoFi Earn solves this mismatch by letting account holders swap their tokenized bank deposits into stablecoins 24 hours a day, 7 days a week.
Tokenized Deposits vs. Traditional Stablecoins
Many investors wonder how tokenized deposits differ from popular stablecoins like USDT or USDCUSDC+0.33%. While both exist as digital units on a blockchain, their underlying legal structures are quite different.
- Issuer Directness: Tokenized deposits are directly issued by a chartered commercial bank (like SoFi Bank), whereas stablecoins are issued by private fintech companies.
- Insurance: Tokenized deposits remain eligible for FDIC insurance while held as cash deposits. Stablecoins generally do not offer government deposit insurance.
- Regulatory Oversight: Commercial bank deposits fall directly under strict banking Supervision and capital requirements.
- Yield Mechanics: SoFi Earn offers native interest directly from the bank, whereas standard stablecoins typically do not pay yield directly to holders due to regulatory limitations in many jurisdictions.
Why This Matters for the Crypto Industry
For years, digital asset funds faced a difficult choice. They could either keep their cash in traditional bank accounts—where it was safe but hard to move quickly into crypto trades—or keep everything in stablecoins on-chain, where they sacrificed deposit insurance and faced issuer concentration risks.
Tokenized deposits aim to resolve this dilemma. They allow fund managers to maintain safety, regulatory compliance, and yield while preserving the instant operational flexibility required for decentralized markets.
Understanding the Risks and Considerations
While bank-issued tokenized deposits bring important improvements to treasury management, investors should keep essential risk factors in mind:
- Interest Rate Fluctuations: The 4.40% APY yield is tied to broader macroeconomic interest rates and variable bank policy. Yields can adjust downward if central bank interest rates fall.
- Stablecoin Conversion Risk: Once funds are converted from tokenized deposits into third-party stablecoins, they leave the bank environment and are no longer protected by FDIC deposit insurance.
- Blockchain Risk: Moving assets onto distributed networks exposes transactions to network congestion, smart contract vulnerabilities, or operational delays.
- Regulatory Changes: Laws governing tokenized deposits and real-world assets (RWA) remain evolving worldwide, which could alter how these assets operate in the future.
Looking Ahead: The Rise of Real-World Asset Tokenization
The launch of SoFi Earn highlights a growing trend across global finance: the tokenization of Real-World Assets (RWA). Major financial institutions are increasingly placing real-world instruments—such as Treasury bills, bank deposits, and credit products—onto blockchain networks.
As banking infrastructure continues to modernize, tokenized deposits from licensed banks could become a standard cornerstone for institutional cash management across both conventional finance and crypto ecosystem operations.
Latest blog posts

Crypto Becomes a Major Weapon in U.S. Elections
Crypto PACs are spending tens of millions on U.S. midterms, but Democratic candidates are turning the topic into a major campaign battleground over political corruption.
|

Bitcoin ETF Buyers Follow Trends, DWF Labs Research Shows
New research from DWF Labs reveals that Bitcoin ETF investors react to past price movements by buying rallies and selling dips, rather than predicting future returns.
|
XRP Ledger Bug Fix Delayed to Nov 4 After Validator Blip
A minor technical delay has pushed back the activation of the XRP Ledger's latest bug fix amendment to November 4 after a brief drop in validator votes.
|