UK Banks Face Over 10,000 Crypto Complaints in 90 Days
The Growing Conflict Between UK Banks and Crypto Users
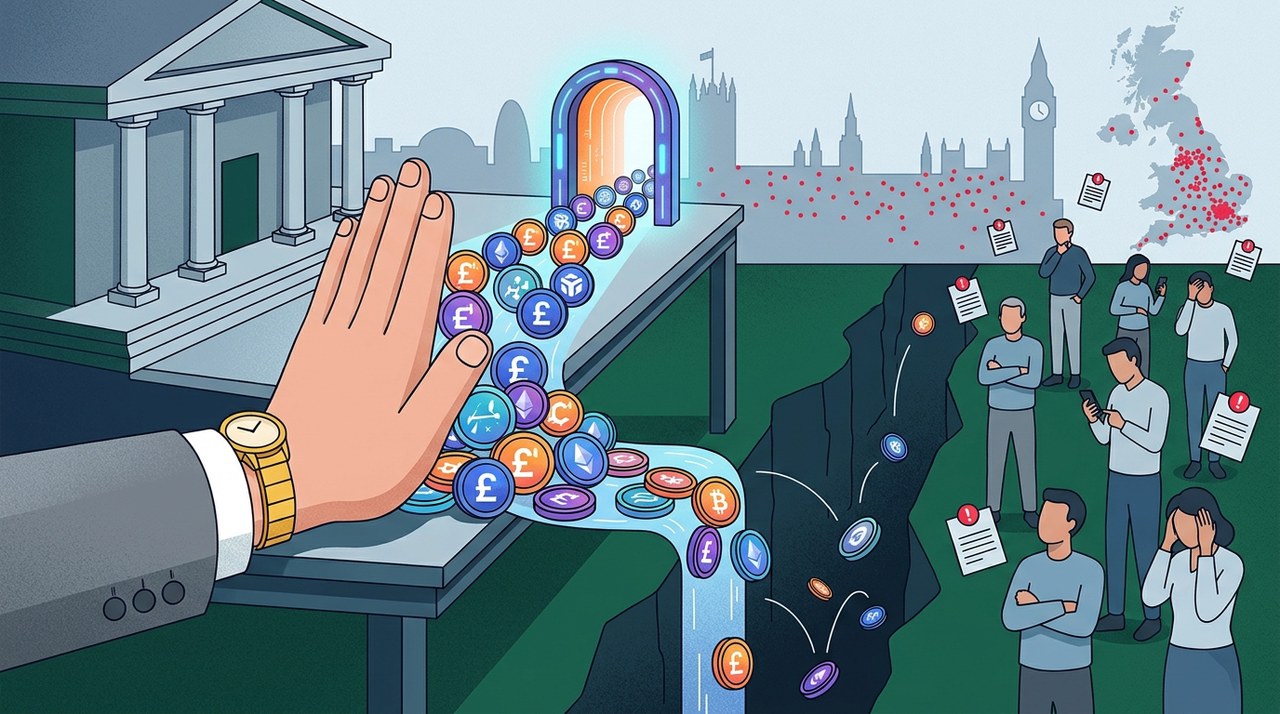
Imagine trying to transfer your hard-earned money to a regulated platform, only to have your bank block the transaction without a clear explanation. For thousands of cryptocurrency users across the United Kingdom, this scenario has become an everyday reality.
The UK government has repeatedly expressed its ambition to turn the nation into a thriving global cryptocurrency hub. However, that vision is running into a major roadblock: traditional high-street banks. Over a single 90-day period, UK bank customers lodged over 10,000 complaints regarding restrictions on crypto transactions.
Breaking Down the Numbers: 10,000 Complaints in 3 Months
According to data released by Stand With Crypto (SWC), an industry advocacy group, a total of 10,092 complaints were filed by 9,800 individual banking customers between May and August. The complaints were collected using an online submission tool.
The data demonstrates that frustration with bank restrictions is widespread throughout the country. Complaints came from residents across all 650 parliamentary constituencies in the UK, showing that this issue affects everyday consumers everywhere, from major financial centers to small rural towns.
Which Banks Received the Most Complaints?
While several major institutions were cited in the report, three prominent high-street banking groups stood out at the top of the list:
- Lloyds Banking Group (which includes Halifax and Bank of Scotland): Received the highest number of complaints, totaling 2,297 (accounting for roughly 23% of the total).
- Barclays: Ranked second, generating 1,569 customer complaints.
- NatWest Group: Placed third, with 1,278 complaints logged by frustrated customers.
It is important to note that the SWC report relies on voluntary submissions from users who chose to use their reporting tool. The dataset is not adjusted for each bank's overall market share or total checking account volume, meaning larger banks with more customers may naturally record higher absolute complaint numbers.
Explicit Limits, Unwritten Rules, and Total Bans
The restrictions imposed by UK financial institutions fall into several distinct categories, ranging from explicit daily caps to outright transaction bans.
Banks that maintain clear, published spending limits accounted for 61% of all complaints. For instance, Barclays explicitly restricts crypto-related transfers to £2,500 ($3,340) per single transaction, with a maximum cap of £10,000 over a rolling 30-day period. NatWest and Santander also publish official daily and monthly transaction limits.
Meanwhile, banks without clear, published restrictions accounted for 28% of the complaints. Lloyds presents a notable example: despite receiving the highest total complaint volume, an SWC audit of bank websites on August 28 revealed that Lloyds had no published official policy restricting crypto transfers, leaving many customers confused when their transactions were unexpectedly blocked.
Outright bans accounted for just under 10% of customer complaints. Institutions such as Chase, Starling, TSB, Metro Bank, and Virgin Money have enacted total prohibitions on crypto transactions. Even digital-first platforms like Revolut, which allows users to purchase digital assets inside its own app, were named in customer complaints regarding external transfers.
Why Fiat On-Ramps Are Essential for Crypto Growth
In the cryptocurrency industry, a 'fiat on-ramp' refers to the mechanisms used to convert traditional money (like British pounds) into digital assets. For most consumers, bank transfers represent the fastest, most reliable, and lowest-cost on-ramp available.
When traditional banks restrict or delay these transfers, they create significant friction for users who are trying to interact with fully regulated and registered cryptocurrency exchanges.
"Bank transfers represent a crucial on-ramp to add money to their account on our platform. We are an FCA-registered crypto asset business, but are subject to the same blanket restrictions as the wider crypto asset sector." — Katie Harries, Head of European Policy at Coinbase
Data cited by Harries from the UK Cryptoasset Business Council underscores the extent of the challenge facing regulated exchanges:
- 40% of attempted bank transfers to FCA-registered crypto exchanges were either blocked or delayed over the past 12 months.
- 70% of surveyed crypto exchanges reported that banking conditions in the UK have become noticeably more hostile over the previous year.
- The majority of crypto exchanges confirmed that customer friction during account funding has steadily increased.
A Political Contradiction: Ambitions vs. Reality
The banking friction highlighted in the report reveals a central contradiction in the UK's approach to digital assets. On one side, public officials continue to express support for Web3 innovation. The push began in 2023 under former Chancellor (and later Prime Minister) Rishi Sunak, who advocated for making Britain a international center for crypto technology.
That supportive stance was reiterated under the current Labour administration by Lucy Rigby, Economic Secretary to the Treasury. In tandem, the Financial Conduct Authority (FCA) is building out a comprehensive regulatory regime aimed at governing digital asset platforms safely.
However, industry leaders argue that government support means little if retail users cannot transfer funds into regulated businesses.
"A country cannot credibly invite innovators in while allowing banks to lock consumers out. This will undoubtedly dampen the growth of the U.K.’s digital asset sector, with ramifications for associate investment here." — Katie Harries, Head of European Policy at Coinbase
Fraud Protection vs. Fair Access: Seeking a Balanced Solution
To understand the issue fully, it helps to look at why banks enforce these restrictions in the first place. Financial institutions face heavy regulatory scrutiny surrounding financial crime, Authorized Push Payment (APP) scams, and money laundering. Because crypto transactions can be irreversible once completed on-chain, banks often err on the side of caution to protect customers from potential fraud.
Advocates like Stand With Crypto agree that protecting consumers from scams is critical. However, they argue that sweeping, blanket bans go beyond reasonable risk management and disadvantage legitimate users who wish to purchase digital assets through fully compliant venues.
Instead of broad bans or hidden rules, advocacy groups are urging banks to adopt clear, transparent policies and assess risk on a case-by-case basis. They also emphasize that consumers should be given straightforward, transparent avenues to appeal when a legitimate transfer is blocked.
"Banks shouldn’t be allowed to apply blanket restrictions across a whole industry. They should take a case-by-case approach, not choke off the entire sector." — Katie Harries, Head of European Policy at Coinbase
What This Means for UK Crypto Investors
For individual consumers in the UK, navigating bank restrictions requires extra care and diligence. Because different institutions enforce vastly different rules—ranging from explicit monthly transfer caps to complete bans—understanding your bank's crypto policies before attempting major transactions is essential.
As the UK continues developing its formal regulatory framework for digital assets, addressing the friction between commercial banks and regulated crypto exchanges remains a key priority for industry stakeholders seeking clear, consistent standards for everyone involved.
Latest blog posts


 +2
Bitcoin Holds Firm Amid Macro Pressure: Weekly Crypto Review
Bitcoin weathered macro turmoil this week as tech stocks stumbled. Here is a friendly breakdown of market trends, stablecoin news, and security alerts.
|

 +2
Solana and Tether Lead New Wave of Real-World Asset Shift
A new report shows capital in real-world asset tokenization is moving away from Ethereum toward lower-cost networks like Solana and BNB Chain.
|
Argentine Court Clears President Milei in LIBRA Case
An Argentine federal judge has dismissed charges against President Javier Milei over the collapsed LIBRA meme coin, though critics claim the ruling is a cover-up.