Tokenized Securities vs Ownership: What Do You Really Own?
Tokenized Securities: Looking Beyond the Market Wrapper
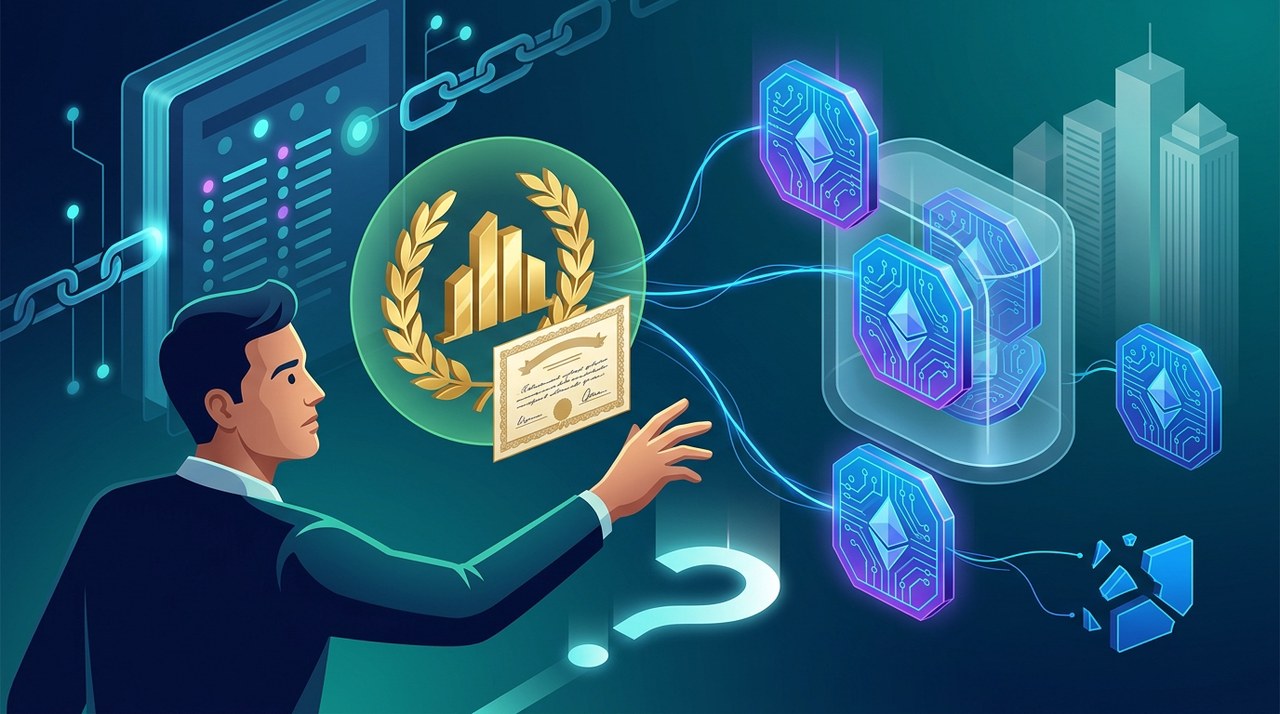
Have you ever noticed digital tokens on crypto trading platforms that mirror the exact price of famous stock market giants? While seeing a familiar company name and a matching price tag is exciting, it does not automatically mean you own actual company shares.
The token sitting in your crypto wallet is a blockchain-based record. What you legally own is decided by the underlying legal setup, known as the asset wrapper. This legal wrapper determines whether you hold genuine equity, an indirect interest through a broker, or simply a claim against a third-party issuer.
Revaz (Rezo) Shmertz, co-founder and Managing Partner at digital asset investment firm BR Capital and founder of Web3 research initiative Beyond Research Labs LLC (BR Labs), provides clarity on this issue. Drawing on over 20 years of financial market experience, Shmertz compares an asset wrapper to a receipt that points to an asset stored somewhere else under a separate set of rules.
These tokenized setups are useful when platforms explain their legal nature clearly and transparently. The real danger happens when a platform sells a wrapper to investors as if it were the actual stock itself. When structural details are obscured, investors are left exposed to unexpected counterparty risks.
Issuance Architecture: Who Issued the Underlying Security?
In January 2026, the U.S. Securities and Exchange Commission (SEC) released a staff statement highlighting how tokenized assets differ. Specifically, the SEC staff distinguished between securities tokenized directly by or for the issuing company and products built by independent third parties.
It is important to note that this SEC staff statement is an informational guide rather than a formal new rule or Commission-approved framework. It applies specifically within the U.S. regulatory environment, but its core lessons apply globally. The legal reality of any token always depends on the specific contract documents and local laws governing it.
Under an issuer-sponsored model, the issuing company or its official agent integrates blockchain records directly into the firm's master shareholder register. In this setup, sending a token to another wallet legally changes who owns the actual share.
Alternatively, an issuer might keep its official shareholder registry off-chain. In this arrangement, transferring a token acts like sending a notification to the company to update its official books, but the token itself carries no shareholder rights.
In both issuer-backed scenarios, the underlying shares and their legal terms establish your rights. The token merely acts as a digital tool to record or move your holding.
Key Tokenized Issuance Structures
- Issuer-Sponsored Direct Tokens: Blockchain records update the official shareholder register directly.
- Issuer-Sponsored Indirect Tokens: Token transfers notify off-chain registers, but the token carries no direct voting or shareholder rights.
- Third-Party Synthetic Tokens: Issued by external companies without the original firm's involvement, giving price exposure rather than equity.
A Tokenized Fund Share Remains a Fund Share
A common point of confusion in digital markets is the difference between buying a share in a fund versus buying shares in individual companies. They are completely different financial investments, even if both use blockchain technology.
When you invest in a mutual fund share, you acquire a stake in a pooled portfolio. You share in the overall gains and losses generated by that pool. This is vastly different from acquiring a specific stock in a private brokerage account.
Consider a tokenized government money market fund. When you buy this token, you own a share in the managed fund, not individual Treasury bills that you selected yourself. The fund's investment mandate, management expenses, and redemption terms are fundamental parts of what you own.
Similarly, holding a token linked to a fund that owns government bonds gives you a fund interest. In contrast, holding a tokenized note issued by a third party and backed by government bonds creates a debt claim against that note issuer. Knowing which assets sit in a pool does not automatically tell you what legal rights you hold.
Intermediary Holdings and Beneficial Rights
Traditional financial markets have long distinguished between registered ownership and beneficial ownership. In countries like the United States, most stocks are held in 'street name.' This means shares are officially registered in the name of a broker or clearinghouse, while the broker keeps private records showing that you are the beneficial owner.
Because of this traditional setup, it would be incorrect to assume that only direct registration counts as real ownership while any intermediary setup is just a fake IOU. Indirect ownership is a standard building block of global finance when governed by proper legal terms.
When reviewing a tokenized asset, the key question is what the intermediary's records legally guarantee for you. A tokenized security entitlement can give you genuine beneficial interest in underlying shares, while a custodial receipt provides proof of that interest without putting your name on the company's register.
Collateralized Assets Are Not Company Equity
Imagine a tokenized debt note whose value tracks a famous stock, with actual shares set aside as collateral. While having collateral provides backing, it does not transform you into a shareholder of that company.
Your right to receive payments comes entirely from the terms of the note. Your rights to the underlying collateral only come into play if the note issuer defaults.
In traditional finance, secured lending and equity ownership are strictly separated. If a note issuer goes bankrupt, you must review the legal contracts to see which assets back the note, who can legally claim them, and how long recovery would take.
A statement that assets are set aside does not guarantee that you have primary priority over other creditors in court. Furthermore, a contractual formula that pays you cash equal to stock dividends does not make you a true shareholder with voting rights. As Revaz Shmertz notes, price exposure and collateral can never replace true shareholder equity.
Price Exposure vs. Real Share Ownership
Conventional structured notes frequently calculate payouts based on stock market indices or individual share prices. Yet, these products remain corporate debts of the party issuing the note.
If you hold a tokenized structured note, your investment relies heavily on the financial health of the note issuer. If the issuer fails, you could lose money even if the underlying company's stock is booming.
Additionally, structured payoff formulas often differ from holding real shares. For example, a tokenized note might track a stock's price on a specific date and settle payouts strictly in cash. This contract might explicitly exclude dividend payouts or cap your potential profits if the stock skyrockets.
According to Revaz Shmertz, these contractual details are critical items that every investor must carefully review rather than assuming all stock-linked tokens offer identical benefits.
Selling Tokens vs. Redeeming Tokens
Investors often confuse selling a token on a secondary crypto exchange with redeeming a token directly through its issuer. They are two entirely separate transactions governed by different rules.
Selling a token requires finding another willing buyer on an open market. Redeeming a token means handing it back to the issuer or its transfer agent in exchange for the underlying cash or assets calculated under formal redemption rules.
For U.S. mutual funds, redemptions are typically priced at the next calculated Net Asset Value (NAV) after an order is received, minus any applicable fees. The SEC emphasizes that calculating this price and actually transferring cash are separate steps; official pricing rules do not promise instant cash in your bank account.
Imagine holding a token that can be transferred wallet-to-wallet 24/7, but the issuer only processes cash redemptions during standard banking hours. Transferring that token on a Saturday night changes who holds the digital asset, but it will not grant access to cash until banking operations reopen.
Furthermore, holding a tokenized note in your self-custody crypto wallet while pledged collateral stays with an institutional custodian does not give your wallet software the legal power to command that custodian. As Shmertz emphasizes, safeguarding your private key guards your wallet, but only formal legal terms dictate your rights to the underlying assets.
What Blockchain Adds to Modern Investments
Revaz Shmertz believes the true promise of tokenization goes far beyond simply placing legacy financial assets onto a blockchain ledger. He envisions financial assets that can move seamlessly across open decentralized finance (DeFi) protocols without artificial access barriers.
At the same time, Shmertz recognizes that neutral blockchain technology allows issuers to build restricted, highly controlled products if they choose. A smart contract accepting a tokenized asset as collateral must evaluate the legal rights of that asset, not just the code moving it.
A tokenized fund share with specific redemption schedules presents very different liquidity questions than a debt note payable only at maturity. Determining whether a DeFi protocol can convert an asset into cash requires analyzing the asset's legal structure, not just its software functions.
Before comparing two tokenized investments, an investor should be able to describe each in an ordinary sentence: what instrument is being acquired, from whom, and what right can be exercised as a result.
If one asset turns out to be a genuine fund share and the other is a third-party debt note, that single sentence tells you far more than the fact that both assets live on a blockchain. The technology improves how investments are transferred, but you must always know what you truly own.
Latest blog posts


How a $1,000 Bet Turned Into a $98 Billion Giant
In 1997, Jeffrey Sprecher bought a near-bankrupt energy platform for $1,000. Today, Intercontinental Exchange owns the NYSE and is worth $98 billion.
|
Can SpaceX Reach a $100 Trillion Market Valuation?
Elon Musk suggests SpaceX could top $100 trillion in a decade, but achieving this milestone depends on massive growth, high-tech breakthroughs, and financial stability.

Ex-White House Crypto Chief Patrick Witt Speaks After Exit
Former White House Crypto Council chief Patrick Witt addressed his departure, sharing optimism for US tech innovation and his plans for the private sector.
|