
Stripe Card Fraud Scheme Ends in Prison Sentence
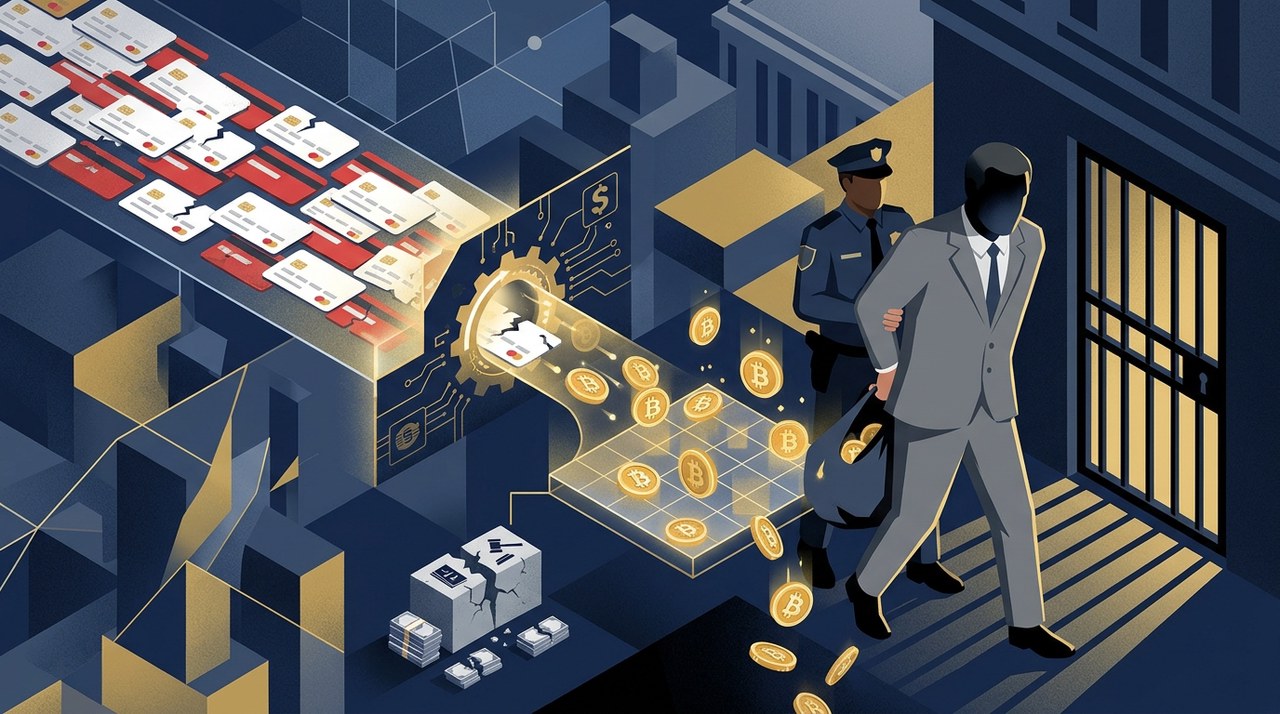
A Fraud Scheme Unravels in Federal Court
A New York man is heading to federal prison after running an elaborate financial scheme. Timothy Wadsworth, 35, converted unauthorized credit card payments into BitcoinBTC-1.26% to enrich himself and his co-conspirators.
The U.S. Department of Justice announced his sentence on October 23. U.S. District Judge Frank P. Geraci Jr. sentenced Wadsworth to 51 months behind bars following his conviction for conspiracy to commit wire fraud and money laundering.
In addition to prison time, Wadsworth must pay $810,965.19 in restitution. He was also ordered to forfeit $810,956.19 in direct wire fraud proceeds.
How Stolen Cards Were Turned Into Bitcoin
Between March 10 and May 15, 2020, Wadsworth teamed up with individuals who provided him with stolen credit card account numbers. He processed these stolen credentials through Stripe, a widely used payment processing service.
During that window, Wadsworth attempted 310 separate charges totaling $1,673,578. While many transactions were flagged or rejected, 116 payments successfully went through initially. These unauthorized charges totaled $730,728.22.
Department of Justice officials confirmed that actual account holders never authorized these transactions. Wadsworth then began a multi-step laundering process to move the stolen cash.
First, he routed payments from Stripe into personal accounts he controlled at HSBC bank and Evolve Federal Credit Union. After the cash arrived, he transferred funds to the major cryptocurrency exchange Coinbase.
Once on Coinbase, Wadsworth purchased Bitcoin and sent it directly to external wallet addresses managed by his partners. Many individual transactions during this payment-to-crypto chain exceeded $10,000.
While digital assets offer fast transfers, they also create a permanent record. Every Bitcoin transaction updates ownership records on the network public ledger, which allowed federal investigators to trace the complete path of the funds.
Multiple Fraud Schemes Totaling Millions in Losses
The payment processor scam was only one portion of Wadsworth illegal operations. Federal records show his schemes between March 2020 and September 2021 created approximately $2.06 million in combined actual and intended losses.
During the pandemic, Wadsworth fraudulently targeted government assistance programs designed to help struggling businesses and unemployed individuals.
- False applications to the Economic Injury Disaster Loan (EIDL) program yielded $161,200.
- Two separate Paycheck Protection Program (PPP) loans paid out $20,833 and $20,416.
- Fraudulent unemployment benefit claims generated roughly $65,896.
Wadsworth also targeted individuals through personal romance scams. In March 2020, he directed a $42,000 wire transfer from a recently widowed woman into his personal account.
An online scammer pretending to be an oil rig worker had convinced the victim to send travel money. Additionally, six other individual victims lost a total of $26,000 across his various schemes.
Broader Enforcement Trends Across Crypto and Traditional Finance
Law enforcement agencies are increasingly focusing on cases where traditional payment fraud intersects with digital assets. Wadsworth case reflects a growing list of global prosecutions.
For instance, a 2021 prosecution in the United Kingdom involved a teenager who operated a fake shopping website. He converted his stolen proceeds into digital currency, resulting in police seizing over 48 Bitcoin.
Federal authorities have also issued public warnings about government impersonation scams. In these schemes, fraudsters trick victims into moving cash via Bitcoin ATMs, wire transfers, and cash couriers under the pretense of protecting their funds.
In a separate case on October 21, federal authorities sentenced individuals involved in laundering $14.5 million in drug proceeds. Intermediaries converted the cash into USDT stablecoins and routed funds through U.S. shell companies to Colombia.
Additionally, the Department of Justice recently indicted a crypto investor over an alleged $20 million fraud scheme that impacted dozens of victims.
Understanding Risk and Regulatory Oversight
These legal actions highlight that cryptocurrency transfers are not beyond the reach of law enforcement. Regulated exchanges operate under strict identity verification standards that link real-world identities to public wallet addresses.
Past performance of digital assets is not a guarantee of future results. Market participants should remain aware of operational risks and ensure they use licensed, compliant platforms when interacting with digital assets.
Latest blog posts
Big Tech Faces Dilemma Over Heavy AI Spending Ahead of Q3
Major tech companies face intense investor scrutiny over artificial intelligence spending, with markets penalizing both cash cuts and heavy investments.
Bitcoin Drops Below $80K: Analyzing Cowen's Macro Roadmap
Bitcoin recently slipped below $80,000 as analyst Benjamin Cowen tracks his nine-step macro roadmap. Here is what could happen next.
|


Ripple Swell 2026 Begins in NYC With 100+ Speakers
Ripple's annual Swell conference opens Oct. 27 in New York, combining three major events to cover stablecoins, institutional finance, and XRP Ledger technology.
|