
SE Asian Central Banks Join Ripple Cross-Border Pilot
A Major Step for Cross-Border Payments
Transferring money across international borders has historically been a slow and expensive process.
Central banks in Southeast Asia are actively working to modernize that financial infrastructure.
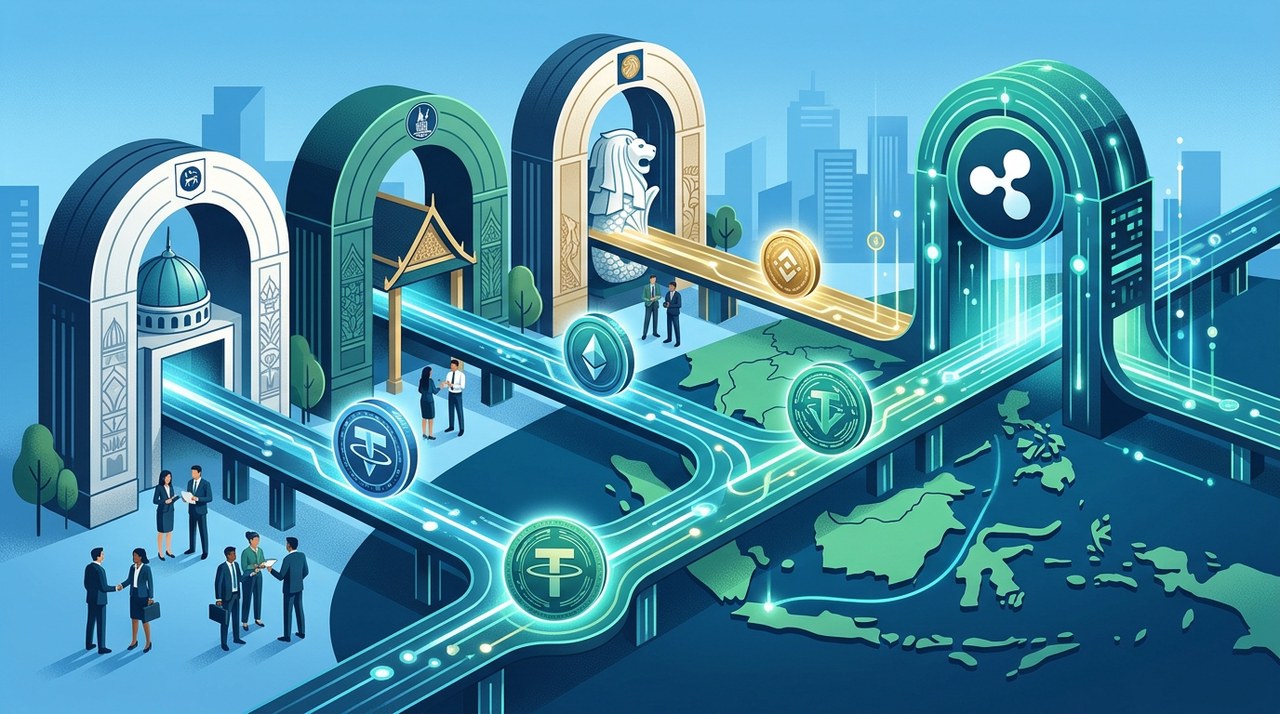
Bank Negara Malaysia and the Bank of Thailand have officially joined Singapore on Project BLOOM.
This initiative explores how stablecoins and tokenized deposits can settle transactions across borders.
Major industry names including RippleXRP-0.56%, Visa, and Mastercard are participating in this broader payment ecosystem.
What Is Project BLOOM?
Project BLOOM is a collaborative initiative originally launched by the Monetary Authority of Singapore.
Its main goal is to create common standards for cross-border digital asset settlements.
Think of traditional international wire transfers like sending a physical letter across the ocean.
The payment passes through several intermediary banks before reaching its final destination.
Each intermediary adds processing delays and additional transaction fees to the transfer.
Project BLOOM tests if blockchain infrastructure can upgrade that experience into something instant.
Understanding Tokenized Deposits and Stablecoins
To understand how this initiative works, it helps to look at two primary technologies.
1. Tokenized Deposits
Tokenized deposits are digital versions of traditional commercial bank deposits stored on a blockchain.
They remain backed 1-to-1 by official money held safely inside bank reserves.
This design allows commercial banks to settle payments instantly without altering standard backing models.
2. Stablecoins
Stablecoins are digital tokens designed to maintain a fixed value relative to fiat currencies.
They offer rapid settlement capabilities and continuous around-the-clock availability.
However, their stability relies heavily on audited reserve management and full regulatory compliance.
The Role of Ripple, Visa, and Mastercard
Private sector technology providers play a significant role alongside public financial authorities.
Ripple provides cross-border liquidity mechanisms and specialized enterprise software built for institutional settlement.
Payment giants Visa and Mastercard bring extensive global network infrastructure and commercial reach.
Together, these entities help central banks connect traditional systems with distributed ledger technology.
Why Regional Cooperation Matters
Southeast Asia represents one of the world's most dynamic regional trade environments.
Millions of workers rely on international remittances to send money back to their families.
Small businesses also conduct daily commerce across neighboring regional borders.
Reducing transfer friction allows merchants and individuals to keep more of their capital.
By collaborating early, Singapore, Malaysia, and Thailand build compatible networks rather than isolated silos.
Important Risks and Operational Challenges
While digital asset settlement offers key operational advantages, central banks proceed with caution.
Aligning financial regulations across three separate legal systems requires significant legal coordination.
Robust cybersecurity measures and anti-money laundering standards must be tested thoroughly.
Blockchain networks must also demonstrate they can handle high transaction volumes without network downtime.
These central bank projects remain in controlled pilot stages before any full public rollout.
Latest blog posts
NY AG Seeks $1.37B From NovaTech Founders
The New York Attorney General is seeking $1.37 billion from NovaTech's founders following an August 2025 default judgment and promoter settlements.

Bitcoin Holds Steady After 3% Drop Amid Stock Market AI Concerns
Bitcoin price volatility cooled down following a 3% dip as Asian stock markets faced renewed pressure over artificial intelligence concerns.
|
XT Exchange on Why Crypto Culture Outlasts Market Downturns
XT Exchange explores how crypto culture, shared terms like HODL, and open community discussions help the industry stay resilient through quiet market cycles.