

Paying Employees and Advisors in Tokens: A Legal Guide
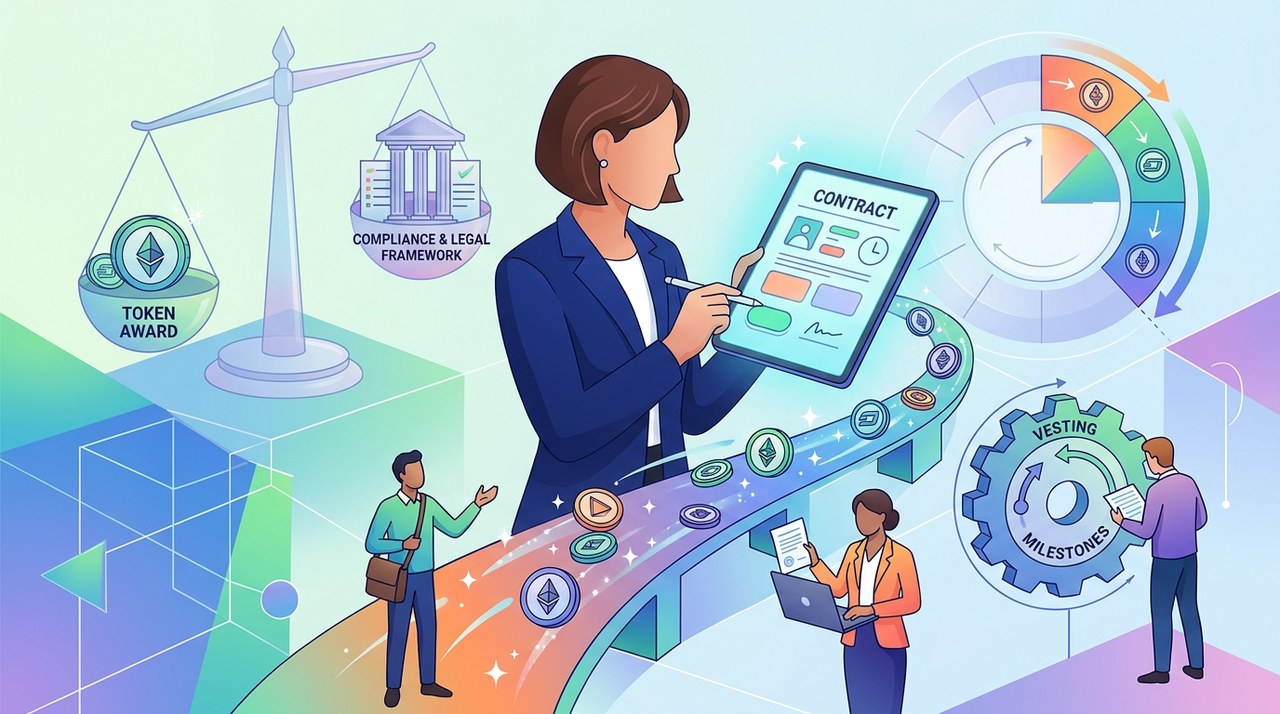
Introduction: The Promise of Crypto Compensation
Imagine hiring a developer and promising them 100,000 tokens vested over two years. Or offering an advisor a small percentage of your token supply to help build your crypto project. Both arrangements sound simple on paper until project launch is delayed, token supply changes, or someone leaves early.
On October 25, 2026, Michael Handelsman from Kelman Law—a firm focused on digital asset commerce—provided guidance on token agreements. At the time of this legal analysis, market benchmarks stood with BitcoinBTC-0.36% at $80,179 (-0.52%) and EthereumETH-1.61% at $2,323 (-1.90%). Past performance of digital assets is not an indicator of future results.
Token compensation agreements must explain exactly what recipients earn, when tokens are delivered, and what happens if the project pivots. For companies with U.S. workers, these arrangements must also align with employment, securities, and tax laws.
1. Identifying Entities and Defining Token Awards
Before offering token compensation, projects must clearly establish legal structures and measurement rules.
Who Promised the Tokens?
Many Web3 companies split operations between different legal entities. For instance, a development company might employ the team, while an independent foundation manages token issuance.
If a dev company promises tokens controlled by a foundation, legal contracts must specify how the employer obtains those tokens. The agreement should clearly state who is responsible if delivery fails. Corporate approvals must also be secured before making formal grants.
Measuring Award Value Clearly
Token allocations must be measurable. A promise of '0.5% of token supply' must define the exact supply metric, measurement date, and how future minting, burning, or token migrations affect the math.
An award granting '$50,000 worth of tokens' needs a specific valuation date, a primary pricing source, and a backup pricing method for illiquid markets. Contracts must also outline attached rights, such as voting power, equity conversions, or revenue sharing.
2. Disentangling Vesting, Delivery, and Transferability
A common mistake in token agreements is confusing vesting, delivery, and transferability. These three concepts refer to separate legal milestones.
Earning vs. Receiving vs. Selling Tokens
Vesting determines when service or performance conditions are met. Delivery marks the physical transfer of tokens to the recipient's wallet. Transferability determines when those tokens can be sold or moved.
These steps can occur months apart. For example, an advisor might vest 25% of an award after six months, receive tokens following a Token Generation Event (TGE), and remain subject to a lockup period.
Contracts must clarify whether vested rights survive if a worker leaves before delivery. Ongoing service conditions should align smoothly with vesting terms and applicable laws.
Setting Clear Vesting Schedules and Milestones
Agreements should clearly state the vesting start date, cliff periods, installment schedules, and performance goals. Performance targets must be objectively measurable with clear dispute resolution procedures.
3. Handling Delayed Launches and Project Changes
Stating that 'tokens will be delivered at launch' leaves room for legal disputes. Project launches rarely happen without adjustments.
What Does 'Launch' Actually Mean?
Contracts must define what constitutes a launch event. Does it mean smart contract deployment, network activation, initial public distribution, or an exchange listing? Defining the precise trigger and delivery deadline prevents misunderstandings.
Backup Plans for Changing Directions
Projects must plan for unexpected shifts. What happens if a project cancels the token, postpones launch indefinitely, changes blockchains, or issues replacement assets?
The contract should outline whether major changes trigger replacement awards, cash payouts, continued rights, or agreement termination. Compliance-related suspensions must include clear grounds, notice requirements, and review protocols.
4. What Happens When Someone Leaves the Project?
Offboarding workers requires clear contractual guidelines to prevent future legal claims.
Handling Departures and Repurchase Rights
Termination clauses should address unvested awards, vested but undelivered tokens, and tokens already transferred. Terms should define 'cause' and clarify outcomes for resignation, termination without cause, death, disability, or company sales.
If a company keeps repurchase or clawback rights, the agreement must state the scope, exercise period, and pricing rules. These terms must comply with local employment and wage protection laws.
Establishing Scopes of Work for Advisors
Advisor agreements should describe specific services, expected availability, deliverables, confidentiality duties, and intellectual property ownership. Clear scopes of work establish a legal link between services rendered and token allocations.
5. Navigating Employment and Wage Laws
Paying team members in tokens does not exempt companies from statutory employment and labor regulations.
Cash Payroll Requirements and Overtime
U.S. federal wage regulations generally require minimum wage and overtime payments to be paid in cash or negotiable instruments payable at par. Paying staff exclusively in project tokens generally fails to satisfy these requirements.
A standard approach is paying minimum wage and base salary via compliant cash payroll, while structuring tokens as separate incentive awards. Federal overtime rules may require bonus token value to be included in regular rate calculations unless specific exclusions apply.
Worker Misclassification Risks
Labeling a worker as an 'advisor' or 'contractor' does not automatically determine their legal status. The Department of Labor provides detailed guidelines on misclassification risks. For international teams, companies must seek local legal counsel in every jurisdiction where workers operate.
6. U.S. Securities Compliance and Rule 701
Token compensation arrangements must comply with federal and state securities laws before offers are extended.
Using SEC Rule 701 Exemptions
SEC Rule 701 allows qualifying non-reporting issuers to offer compensatory securities under written plans. It includes specific offering caps, disclosure rules, and eligibility criteria.
Eligible advisors must be natural persons providing genuine services to the issuer. Crucially, advisor services cannot involve fundraising, promoting the token, or maintaining a secondary market for the asset.
Restricted Securities and Foundation Entities
Rule 701 covers direct issuer transactions. It does not automatically cover resale transfers where an employer holds tokens issued by a separate entity like a foundation.
The SEC considers securities issued under Rule 701 to be restricted securities. Vesting does not make them freely tradable. State blue-sky laws and federal anti-fraud provisions still apply.
7. Tax Implications: IRS Rules, Section 83, and Section 409A
Tax structures can create immediate financial liabilities for both workers and companies if not structured properly.
Income Tax Measurement and Withholding
Under IRS Notice 2014-21, paying workers in convertible virtual currency creates compensation income measured by the asset's fair market value in U.S. dollars at receipt.
Employee token payments carry tax withholding, employment tax, and Form W-2 reporting obligations. Independent contractors recognize service income subject to self-employment taxes.
Section 83 and Section 83(b) Elections
Under Internal Revenue Code Section 83, restricted compensation is taxable once property transfers and becomes substantially vested under tax rules. Taxable amounts reflect fair market value at vesting minus any price paid for the property.
Contractual vesting and tax recognition dates may not coincide. An employee holding illiquid tokens might face cash tax liabilities before they can sell their tokens. Employers need operational plans for payroll tax deposits.
For transfers of substantially non-vested property, workers may file a Section 83(b) election within 30 days of transfer to accelerate income recognition to the transfer date. However, if tokens are later forfeited, previously reported income generally cannot be deducted.
Deferred Compensation and Section 409A
Promising to deliver tokens in a future tax year can trigger Section 409A deferred compensation rules unless an exemption applies. If Section 409A applies, a token launch or exchange listing is not automatically a valid payment trigger. Counsel should review delivery dates prior to granting awards.
8. Practical Implementation and Smart Contract Alignment
Once legal terms are established, technical execution must match written contracts.
Agreements should specify wallet-verification steps, supported blockchain networks, gas fee responsibilities, and procedures for failed transfers.
Written contract terms must align with underlying smart contracts controlling vesting or releases, explaining how discrepancies are resolved. Agreements must also include clear governing law and dispute-resolution clauses.
Key Checklist for Token Agreements
- Identify issuing and employing legal entities clearly
- Define supply calculation metrics, valuation dates, and illiquid pricing fallbacks
- Separate contractual vesting from delivery timing and transfer lockups
- Establish concrete definitions for project launch triggers and delay contingencies
- Maintain compliant fiat cash minimum wage alongside token incentives
- Verify SEC Rule 701 eligibility for non-promotional advisor services
- Plan for IRS Notice 2014-21, Section 83(b) election deadlines, and Section 409A compliance
- Ensure smart contract code matches written legal agreements
Final Takeaways
Kelman PLLC assists digital asset companies with commercial contracts and regulatory queries. Projects planning employee or advisor token awards should compile proposed allocations, token distribution plans, corporate structures, and existing service contracts for legal review.
Attorney Advertising. This article provides general informational content and does not constitute formal legal advice. Contacting the firm does not establish an attorney-client relationship.
Latest blog posts

XRP Death Cross Complete: Key Price Levels to Watch
XRP has formed a technical death cross pattern on its daily chart, pointing to weak momentum as traders watch key support and resistance levels.
|
 +1
Dogecoin Community Warned Following Keystone Security Breach
Hardware wallet maker Keystone revealed a data breach involving customer shipping details. Dogecoin community members urge users to prepare for potential phishing scams.
|
Mysterious Poem Found Written on Bitcoin Blockchain
Researchers at Galaxy Digital discovered 28 mysterious poem transactions embedded directly into the Bitcoin blockchain over a twelve-day period.
|