

Will Stablecoins Survive Once Traditional Banks Catch Up?
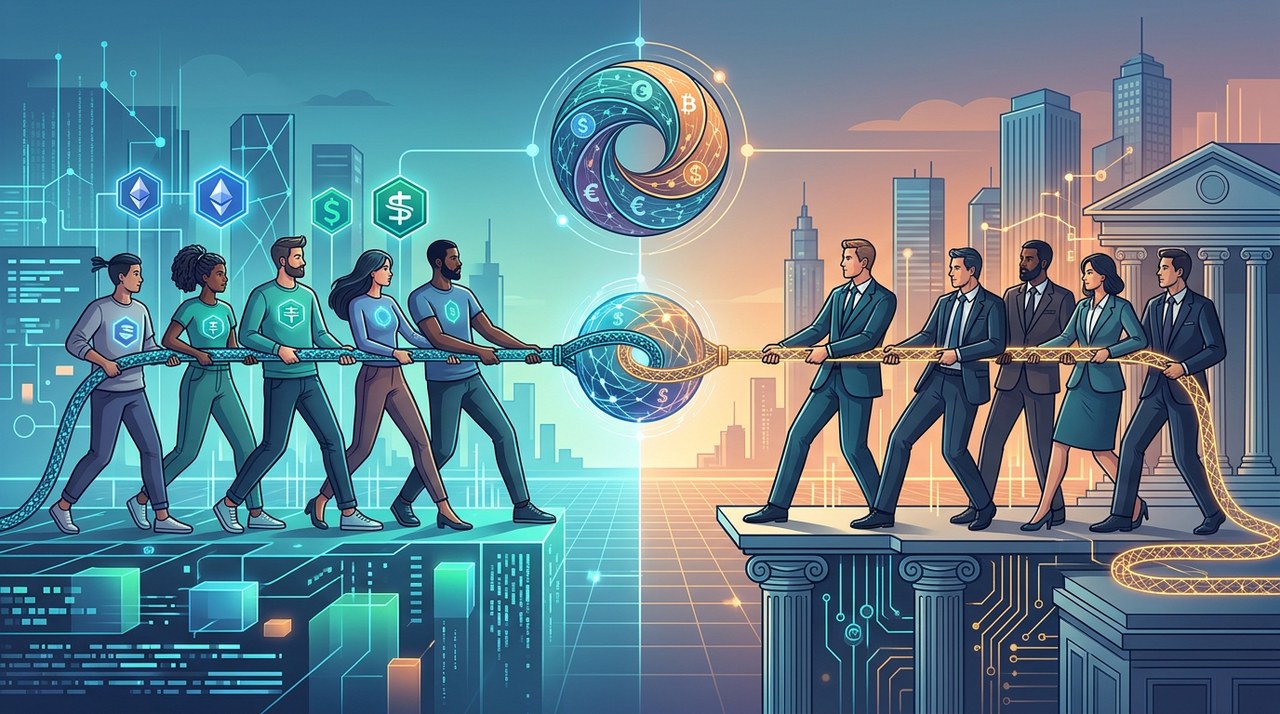
The Digital Money Tug-of-War
Imagine sending money across the world as easily as sending an email. For years, traditional bank transfers took days and charged high fees. Stablecoins stepped in to fix that problem.
Stablecoins are digital tokens designed to track the value of national currencies like the US dollar. They offered fast, round-the-clock transfers on blockchain networks. Because of this speed and convenience, stablecoins quickly became the backbone of the crypto trading ecosystem.
However, the line between traditional banking and crypto is starting to blur. As major commercial banks begin building their own digital money networks, a big question emerges: can independent stablecoins keep their lead once big banks catch up?
Who is Raising the Question?
This question was recently highlighted by Alessandro Hatami. He is the founder of fintech consulting firm Pacemakers and the former Chief Operating Officer of Digital Banking at Lloyds Banking Group.
Because of his extensive background at the highest levels of retail banking, Hatami brings a realistic corporate perspective to the crypto debate. He points out that as crypto firms try to look more like regulated financial institutions, banks are simultaneously adopting blockchain technology.
As crypto firms and banks converge, it is fair to ask what lasting advantage stablecoins have.
Why Stablecoins Won the First Round
To understand where digital money is going, it helps to look at why stablecoins became popular in the first place. Early crypto traders needed a safe harbor during volatile market swings without converting back into fiat cash every time.
Stablecoins solved several problems that traditional banking systems suffered from for decades:
- Always Open: Blockchain networks operate 24 hours a day, 7 days a week, unlike traditional banking hours.
- Global Accessibility: Anyone with an internet connection can set up a wallet and receive digital dollars without needing a traditional bank account.
- Seamless Tech Integration: Stablecoins can easily connect with smart contracts and decentralized finance (DeFi) platforms.
- Instant Settlement: Payments settle in minutes or seconds rather than taking multiple business days.
How Traditional Banks Are Catching Up
For a long time, traditional banks watched the crypto space from the sidelines. However, financial institutions are no longer standing still. They are actively building upgrades to their payment architecture.
1. Tokenized Bank Deposits
Instead of using third-party stablecoins, major financial institutions are testing tokenized deposits. These are regular bank deposits converted into digital tokens on a ledger. Tokenized deposits offer 24/7 instant transfers while remaining directly tied to the commercial banking system.
2. Central Bank Digital Currencies (CBDCs)
Governments around the world are exploring or testing official central bank digital currencies. A CBDC provides a digital version of cash issued directly by a nation's central bank, offering high security and official backing.
3. Commercial Bank Stablecoins
Some of the largest global banks have already developed private blockchain payment networks for their corporate clients. These networks allow institutions to transfer huge sums instantly without relying on non-bank crypto issuers.
What Lasting Advantages Could Stablecoins Retain?
If commercial banks offer instant digital transfers backed by deposit insurance, what unique edge remains for non-bank stablecoin issuers? Analysts and industry watchers see a few key areas where private stablecoins might still hold ground.
First, openness remains a core factor. Most bank-issued payment networks operate inside walled gardens, meaning only approved institutional clients can access them. In contrast, popular stablecoins run on public blockchains like EthereumETH-5.74% and SolanaSOL-6.20%, accessible to anyone globally.
Second, stablecoins are deeply woven into decentralized finance. Automated protocols, yield platforms, and decentralized exchanges rely on permissionless stablecoins to function smoothly.
Potential Future Scenarios
Predicting the future of digital money involves several moving parts. Below are three potential ways the landscape could evolve over the coming years.
Scenario A: Stablecoins Dominate Open Blockchains
Under the assumption that public blockchain adoption continues growing rapidly, private stablecoins could remain the primary medium of exchange for decentralized applications. However, if governments enforce tight regulatory requirements on unhosted wallets, growth in retail international payments could slow down.
Scenario B: Banks Take Over Mainstream Commerce
If commercial banks successfully roll out user-friendly tokenized deposits with instant clearing and consumer fraud protections, everyday consumers might prefer bank solutions. In this scenario, non-bank stablecoins could become specialized tools primarily used for crypto trading.
Scenario C: Hybrid Coexistence
Assuming regulatory frameworks become clearer globally, private stablecoin issuers might partner directly with regulated banks. Stablecoins could serve as open international bridge currencies, while bank tokens handle domestic institutional settlements.
Understanding the Risks and Realities
While digital payment innovation offers convenience, users must remain mindful of the risks involved in different types of digital assets.
Non-bank stablecoins carry smart contract risks, regulatory compliance challenges, and counterparty risks depending on how reserves are managed. On the flip side, bank-issued digital currencies may offer stronger regulatory protections, but they often lack privacy and open access.
As the financial world moves forward, the boundary between crypto tech and legacy banking will continue to shrink. Whether stablecoins maintain their dominant role or evolve into specialized infrastructure, the competition is actively reshaping how money moves worldwide.
Past performance of any digital asset or financial institution is not a guarantee of future performance. Users should carefully evaluate operational risks and regulatory developments before holding or transferring digital assets.
Latest blog posts
Proton Mail: Protecting Your Crypto via Inbox Security
Discover how Proton Mail uses end-to-end encryption, email aliases, and PhishGuard to protect your crypto accounts from hackers and phishing attacks.

Bitcoin vs Telegram Wallets: What the Data Really Means
Recent data shows Bitcoin wallet numbers slightly dropping while Telegram wallets surge. Here is a closer look at what these statistics actually mean for investors.
|
Decrypt Teams Up with Helius for Private Solana Transfers
Decrypt has partnered with Solana infrastructure provider Helius to add confidential transfers powered by Solana Privacy Rings to the Decrypt Money Account.
|