


US Senate Findings Put GCC Stablecoin Use Under Spotlight
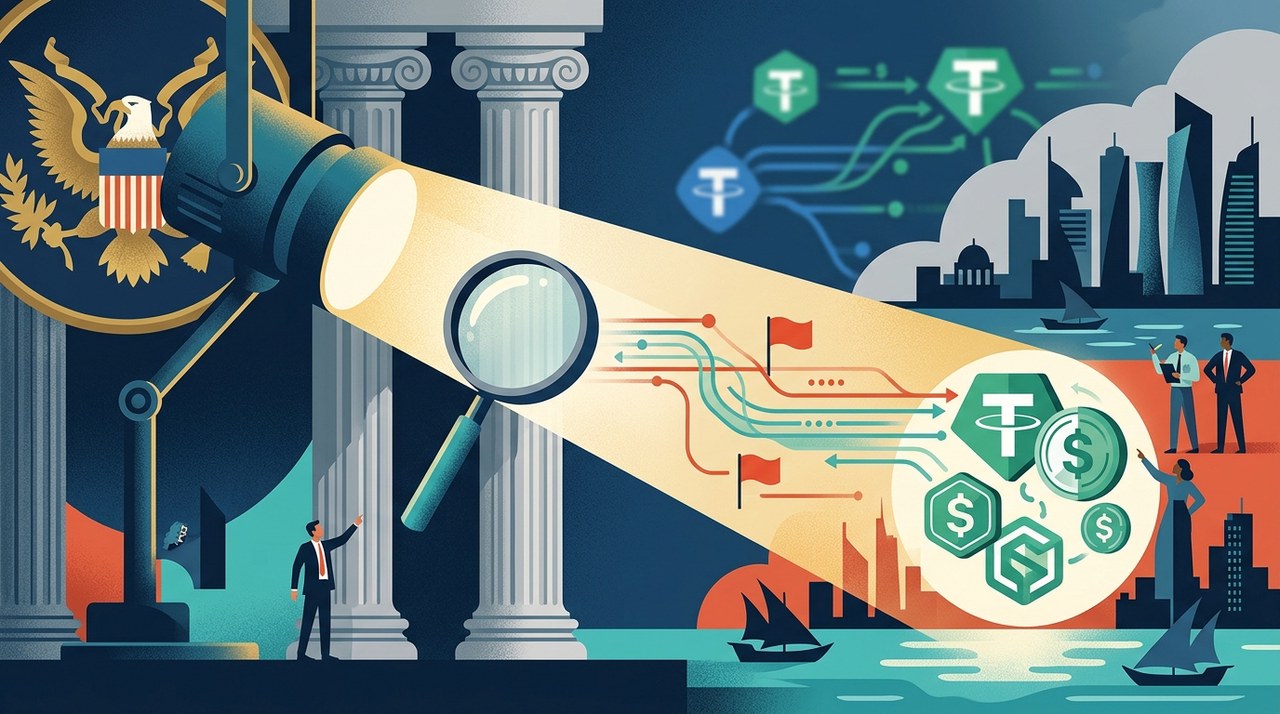
U.S. Senate Investigation Triggers Sanctions Alarm in the Gulf
On October 7, 2026, a major regulatory development began impacting the global cryptocurrency industry. At the time of the findings, BitcoinBTC-2.08% was trading at $83,749 (down 2.60%) and EthereumETH-1.37% was at $2,596 (down 4.18%). Please note that past performance of digital assets is no guarantee of future results.
A new report from the U.S. Senate Permanent Subcommittee on Investigations (PSI) revealed that stablecoins, particularly TetherUSDT+0.50%, serve as a major liquidity engine powering Iran's shadow banking apparatus.
This finding signals a clear message from Western authorities: passive or reactive compliance is no longer enough. For licensed Virtual Asset Service Providers (VASPs) operating across the Gulf Cooperation Council (GCC), this inquiry could significantly reshape how counterparty risk is managed.
Why the GCC Region Faces Heightened Sanctions Risks
The Gulf region shares close geographic proximity to Iran and maintains active cross-border trade networks. Because of this, separating legitimate local commerce from sanctioned proxy activity requires precise wallet attribution.
As a direct result, regional crypto exchanges, over-the-counter (OTC) desks, liquidity providers, and payment processors may need to reassess their operational relationships to prevent illegal exposure.
The Domestic Bank Account Myth
Many local merchants assume that receiving local currency into a domestic bank account insulates them from crypto sanctions risks. Legal experts warn that this belief is incorrect.
Soham Jethani, a partner at law firm Septten, explains that legal liability does not simply start or stop at bank settlement. There is no single universal point in a payment chain where liability attaches.
"The relevant prohibition may concern dealing with a designated person, making funds or economic resources available, or handling property in which a designated person has an interest," Jethani noted.
Jethani emphasized that receiving fiat currency does not erase underlying compliance obligations. Merchants must understand their customers, their payment structures, and the controls deployed by their payment providers.
While a wallet risk flag warrants investigation rather than serving as automatic proof of a violation, the actual operational burden to check these details falls on licensed VASPs rather than individual merchants.
Token Ownership vs. Contractual Claims
Deeper legal questions arise when transactions involving local currency-backed stablecoins touch flagged wallets or high-risk exchanges. Specifically, uncertainty remains over whether a merchant ever legally takes title to those tokens or merely holds a contractual claim for fiat against their payment processor.
Jethani highlighted that a token's name or denomination does not determine legal ownership. Instead, title depends entirely on underlying contracts and actual payment flows.
"That distinction affects custody, insolvency exposure, and which assets or claims the merchant holds," Jethani explained. "It does not answer every sanctions question. A prohibited transaction can involve services or making resources available without the merchant owning the tokens."
He added that an indirect or historical wallet connection does not automatically establish a violation under U.S. Office of Foreign Assets Control (OFAC) or UAE sanctions regulations. Enforcement depends on the applicable sanctions regime, the parties involved, and the specific facts surrounding a transaction.
Understanding Secondary Sanctions Exposure
Accepting globally traded stablecoins can expose businesses to secondary sanctions risks from foreign regulatory regimes, even when transactions appear purely domestic.
Secondary sanctions allow jurisdictions, particularly the United States, to penalize non-U.S. entities or individuals for dealing with sanctioned parties, even without a direct territorial link. For example, a non-U.S. bank that knowingly facilitates a major transaction for a sanctioned Iranian financial institution could face severe restrictions, including potential exclusion from the U.S. financial system.
"The transaction may appear domestic, while the stablecoin, its issuer, one of the parties' wallets or wallet providers, the on-ramp/off-ramp exchange, or potential custodian or other intermediary may be connected to a sanctioned party or restricted activity," Jethani warned.
Therefore, settling transactions in local currency through a bank does not eliminate underlying legal risks. Instead, it can obscure upstream exposure, where an illicit counterparty or intermediary creates compliance risks for other participants.
Real-Time Retail Checkout and Pre-Screened Systems
Screening transactions during instant retail checkouts must happen in seconds, which presents technical challenges for traditional blockchain analytics tools.
Jethani pointed out that real-time checks rely heavily on timely, high-quality data. However, data accuracy can be affected by attribution delays involving newly created wallets, mixing in exchange hot wallets, and complex cross-chain bridges.
Fortunately, in regulated markets like the UAE, these real-time retail risks are mitigated because transactions are "risk-fenced" long before customers reach the checkout counter.
Under this framework, consumers use wallets associated with licensed UAE exchanges, where assets undergo continuous pre-screening and monitoring. Suspicious funds can be frozen before a point-of-sale transaction starts, while recipient merchants undergo prior know-your-customer (KYC) onboarding before accepting payments.
While no system is completely foolproof, pre-screening both sides of a transaction creates a strong barrier against illicit activity across daily retail transactions.
Regulated Intermediaries Bear the Operational Burden
Ultimately, legal liability and operational risk remain concentrated on the licensed VASP processing the transaction.
Regulated crypto platforms that facilitate on-ramp and off-ramp services carry the responsibility of conducting thorough counterparty assessments, enforcing Travel Rule requirements, and performing comprehensive sanctions screening.
"The duty is always on the regulated player in-between the transaction to take responsibility for the counterparties," Jethani said. "If things go wrong, they will be the ones held up as in violation and subject to fines and penalties."
Jethani emphasized that regulatory clarity benefits compliant market participants because licensed businesses have strong incentives to maintain their standing.
"People are working hard to be able to be licensed to provide this service, and they will not jeopardize their hard-won licenses for a single transaction," Jethani said. "It is not worth the risks, monetarily or reputationally, no matter who is on the other side."
This rigorous oversight has helped strengthen the UAE's standing as a hub for digital asset firms. Jethani highlighted the thorough testing and compliance checks companies undergo during licensing, noting that these safeguards support the country's position with the Financial Action Task Force (FATF) as its digital asset sector grows.
U.S. Blacklists Iranian Crypto Exchange Bitbank
Demonstrating these heightened enforcement efforts, the United States recently blacklisted Iranian cryptocurrency exchange Bitbank and its software developer over alleged sanctions-evasion activity. The U.S. Department of the Treasury stated that financier Babak was linked to facilitating these illicit transfers, which involved hundreds of millions of dollars in Bitcoin.
Latest blog posts
What Is Bitcoin's Power Law and Why Is $62K Important?
Fidelity's Jurrien Timmer highlights Bitcoin retesting its $62,000 Power Law support line as macro liquidity conditions shift.
|

DBS and Circle Partner for 24/7 Institutional USDC Access
Asian institutions will soon be able to convert U.S. dollars to USDC around the clock through a new partnership between DBS Bank and Circle.
|
DBS Partners with Circle for 24/7 USDC Stablecoin Access
DBS Bank has partnered with Circle to enable 24/7 USDC minting and redemption for institutional clients across Asia.
|