Launching a Stablecoin: Become an Issuer or Partner?
The Big Question Before Launching Your Stablecoin
Imagine a merchant steps up on a Friday afternoon wanting to redeem 100,000 of your company's stablecoins for real US dollars. Who actually owes them that cash?
Before picking a blockchain network or negotiating transaction fees, every payments company must answer this exact legal question. Michael Handelsman from Kelman Law breaks down the choices in this digital asset legal guide.
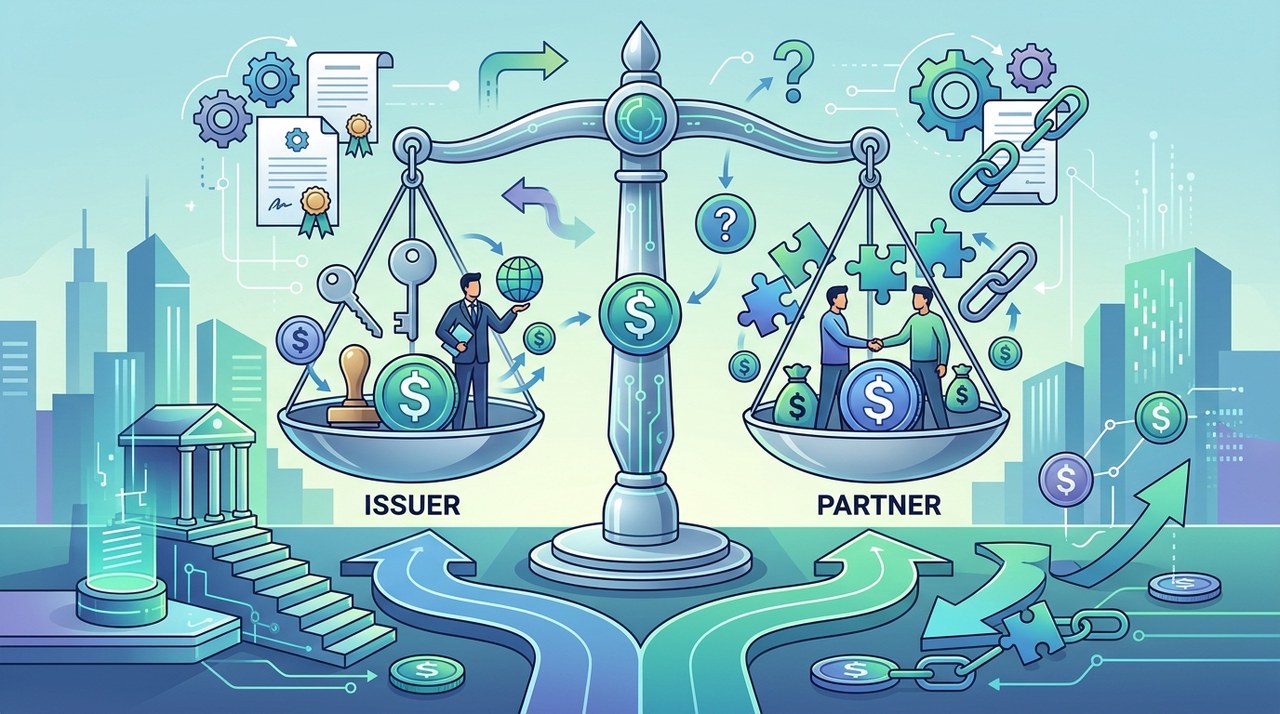
Essentially, companies have two main paths: become a permitted payment stablecoin issuer themselves, or partner up with an existing licensed issuer. Both options let you put your brand on the coin, but they come with very different legal burdens, costs, and responsibilities when things go wrong.
Path 1: Becoming a Licensed Stablecoin Issuer
Under the GENIUS Act, a payment stablecoin is defined largely by the issuer's obligation to redeem, convert, or repurchase the asset for a fixed monetary value. Once this regulatory framework takes full effect, companies wanting to issue tokens in the US must officially qualify as permitted issuers.
Your exact path to becoming an issuer depends heavily on your company's corporate structure and state versus federal regulators.
Federal Approval Pathways
A qualifying nonbank fintech can apply directly to the Office of the Comptroller of the Currency (OCC) to become a federally qualified issuer. Uninsured national banks or eligible federal branches can also seek OCC approval.
On the other hand, an insured depository institution takes a different route. It applies through its primary federal payment stablecoin regulator to issue tokens via a subsidiary. Keep in mind: simply signing a banking services agreement with an insured bank does not make your fintech a bank subsidiary!
Timing is critical for newcomers. As of November 10, the OCC's application portal is not yet accepting applications or waiver requests. Prior approval requirements generally begin on January 18, 2027.
The OCC makes a clear distinction between existing US issuers with complete applications pending before January 18, 2027, and brand-new entrants. New players are generally expected to secure full approval before starting operations, and simply submitting an application does not give you permission to launch.
State Approval Pathways
What if you prefer a state-level setup? Eligible state-qualified issuers with no more than $10 billion in consolidated outstanding issuance can opt for state supervision—provided the state regime is substantially similar to the federal framework.
Note that this $10 billion cap measures total tokens outstanding across the issuer, not annual transaction volume or sales of one single branded token. Also, while the U.S. Treasury certifies state regulatory frameworks, approving an individual issuer is a separate decision. Founders should verify both steps with their proposed home-state regulator.
If your outstanding tokens cross that $10 billion threshold, the GENIUS Act generally requires you to transition to federal oversight within 360 days, unless you secure a specific waiver.
What Running an Issuance Operation Requires
Becoming a direct issuer means building a business resilient enough to handle high redemption demand, even during difficult market stress.
- 1-to-1 Reserve Backing: Maintaining eligible reserve assets backing outstanding tokens at least one-to-one.
- Liquidity Access: Ensuring rapid cash access whenever token holders request redemptions.
- Accurate Reporting: Producing precise, regular reserve reports for regulators and the public.
- Reconciliation Capabilities: Employing dedicated staff to reconcile bank balances with blockchain ledger records.
Direct issuance makes financial sense when having total operational control is critical to your business model, and your company has the capital to fund these compliance requirements even if adoption moves slower than expected.
Path 2: Partnering with an Issuer (White-Labeling)
If your core strength lies in reaching merchants and integrating payments into their accounting software, partnering with an established issuer might be the smarter route.
In a white-label arrangement, your fintech brings the customer interface and brand recognition, while another entity actually issues the token and carries the legal obligation to redeem it for dollars.
The OCC's final rule published on October 23 confirms that issuers are not limited to just one brand. However, for issuers under OCC jurisdiction, the rule mandates clear redemption disclosures identifying the true issuer. If distinct reserve pools back different branded tokens, monthly reports must break down each reserve pool separately.
Remember: a distinct ticker symbol alone tells a merchant nothing about whether their token has a separate reserve pool!
Due Diligence Before Signing a White-Label Deal
Before signing a partnership agreement, ask your prospective issuer for three key operational facts:
- Their exact legal entity name and corporate setup.
- Their current legal authority to issue payment stablecoins.
- Their explicit compliance roadmap for operating after the January 18 deadline.
If your partner expects an approval or waiver, make your product launch strictly conditional on proof that they obtained the necessary legal authority. Also, review your own role carefully: an issuer's regulatory authority does not automatically cover a distributor that handles merchant funds, manages wallets, or converts tokens to fiat currency.
Essential Contract Terms Before Minting the First Token
Before minting your very first stablecoin, your legal agreement with an issuing partner must explicitly resolve several operational scenarios.
1. Token Creation and Minting Authority
Suppose a merchant wires $100,000 on a Friday afternoon. Your fintech system gets a transfer notification, but the issuer's bank hasn't confirmed receipt yet. Can your software automatically mint 100,000 tokens anyway?
Your contract must clearly define what counts as settled funds, who verifies receipt, and who holds authorization to trigger a mint. Test these answers against administrative tools, API permissions, and multi-sig signing keys. An issuer's right to reject a mint is useless if a distributor can execute it unilaterally.
2. Redemption Flow and Holder Payouts
A merchant receiving tokens from customers might not hold an account directly with the issuer. Your terms must state whether that merchant can redeem tokens directly, must complete onboarding first, or must rely on an intermediary.
Specify transaction fees, processing cutoffs, token burning timing, and who pays if tokens burn successfully but the bank transfer fails. Testing this exact failure scenario before launch ensures your support team knows how to resolve unpaid claims quickly.
3. Error Handling, Compliance, and Outages
Assign clear responsibilities for screening users, escalating suspicious activities, fulfilling legal court orders, and fixing balance discrepancies. Provide the issuer access to necessary records to supervise delegated compliance work.
Negotiate indemnity clauses covering losses from unauthorized mints, compromised private keys, or incorrect payouts. Remember that indemnity agreements split costs between companies—they cannot override statutory duties or provide cash to merchants during a banking outage.
4. Partnership Off-boarding and Exit Strategy
Stopping new token minting is simple, but outstanding tokens will stay in user wallets indefinitely. Your contract must fund and delegate ongoing redemptions, customer notices, record keeping, and technical support.
If your fintech reserves the right to switch issuing partners later, define clearly how users will distinguish old tokens from new ones and who stays responsible for legacy assets.
Frequently Asked Questions (FAQ)
Do we need a custom branded token to offer stablecoin payments?
No! If your goal is settling payments rather than issuing currency, you can integrate existing popular stablecoins. This avoids creating a redemption obligation, though custody, exchange, and transfer services still require their own regulatory licensing analysis.
Can we outsource reserve management if we become an issuer?
Yes, within regulatory guidelines. The OCC's final rule lets covered issuers hire third-party asset managers for reserve management. However, the issuer remains fully responsible for oversight, accurate reporting, and keeping enough cash liquidity to meet user redemptions.
What should we ask a prospective issuing partner to demonstrate?
Request a live walkthrough of a full minting cycle, a redemption cycle, and a simulated failed bank payout using actual accounts and signing permissions. Compare this workflow against customer disclosures to ensure all legal decision-makers match across software, contracts, and marketing promises.
Legal Context & Disclaimer
This legal analysis was brought to you by Law and Ledger, a crypto legal news segment by Kelman Law (Kelman PLLC), a law firm focused on digital asset commerce and regulatory compliance.
Attorney Advertising: This article provides general educational information and does not constitute formal legal advice. Companies evaluating stablecoin issuance or white-label partnerships should consult legal counsel regarding their specific funds flow and regulatory obligations.
Latest blog posts

Fidelity's Timmer Explains Why Bitcoin Correlation Rose
A sudden stock market selloff driven by tech fears caused Bitcoin and other assets to temporarily move in sync with equities, according to Fidelity's Jurrien Timmer.
|

Bitmine Reports $6.3 Billion Annual Loss as Ether Drops 44%
Bitmine posted a $6.3 billion net loss in its latest fiscal year, driven largely by $6.23 billion in unrealized paper losses on its Ether holdings.
|
Initia Security Breach: $3.27 Million Lost in Second Exploit
Blockchain project Initia suffered its second exploit in three weeks after an attacker used compromised cloud credentials to move $3.27 million in assets.