


Bitcoin-Backed Loans: How to Borrow Cash Against BTC
What Is a Bitcoin-Backed Loan?
Imagine owning a valuable asset that keeps growing over time. You need cash for a house deposit, a business expense, or a tax bill. Selling that asset gives you cash, but it forces you to give up future gains and potentially triggers a tax bill.
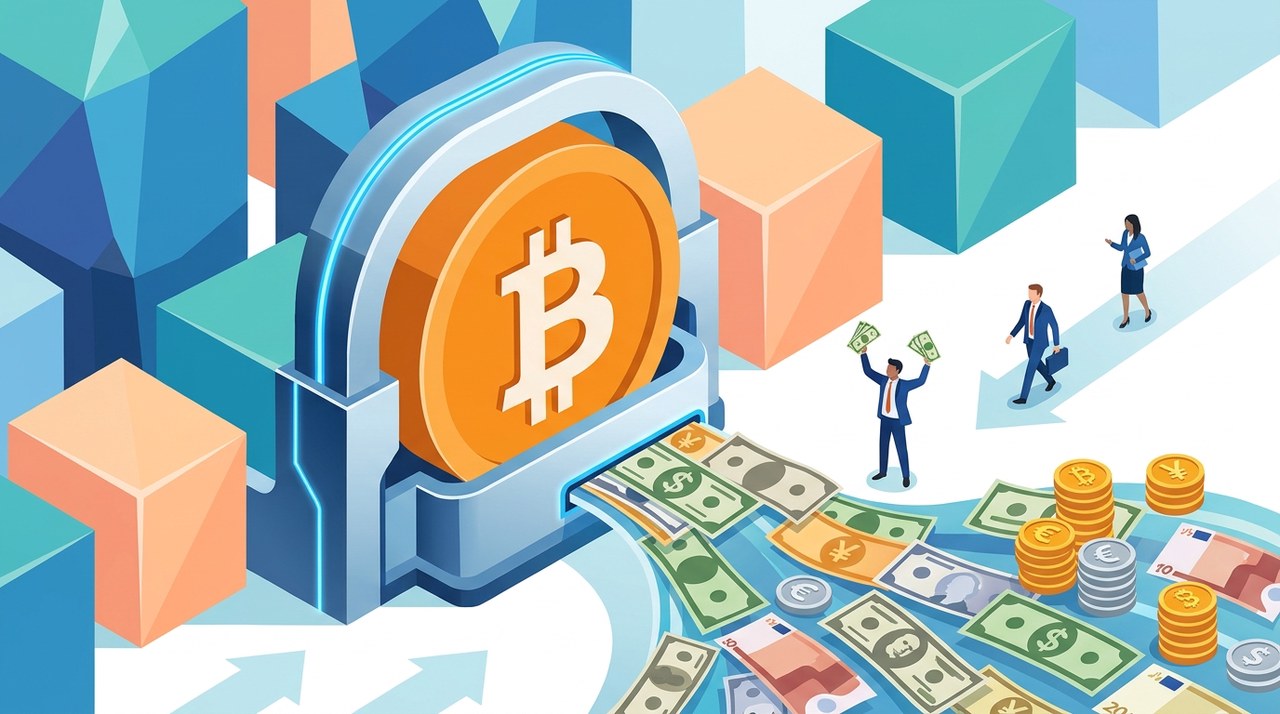
A Bitcoin-backed loan offers an alternative solution. You deposit your Bitcoin as collateral with a lender or smart contract. In return, you receive cash or stablecoins like USDCUSDC-0.24% without selling your underlying coins.
Borrowing against assets is an established concept in finance. People have pledged real estate, stocks, and gold for decades. The key difference here is the asset class: Bitcoin trades continuously worldwide and experiences rapid price movements.
Past performance of digital assets is not a guarantee of future performance.
Why Do Crypto Holders Use Bitcoin Loans?
The primary advantage is liquidity without forfeiture. Selling Bitcoin often triggers capital gains tax depending on your local regulations. Taking out a loan allows you to obtain cash while maintaining your underlying Bitcoin position.
Because your Bitcoin backs the loan, lenders place less emphasis on traditional credit scores or income verification. This setup makes borrowing fast and straightforward.
CeFi vs. DeFi: Two Ways to Borrow
You can choose between centralized platforms or decentralized smart contracts to secure a loan.
Centralized Finance (CeFi)
Centralized loans come from regulated companies such as Ledn, Strike, Unchained, Nexo, and Coinbase. You complete identity checks (KYC), and the provider or its designated custodian secures your Bitcoin.
Decentralized Finance (DeFi)
Decentralized loans run on automated blockchain protocols like AaveAAVE-7.35% and MorphoMORPHO-3.02%. A smart contract manages the process directly. To use native Bitcoin in DeFi, it is usually converted into wrapped tokens on other networks.
Wrapped Bitcoin is a token on another blockchain, like EthereumETH-1.98%, backed 1:1 by real BTCBTC-1.02% held in secure custody.
How Does Loan-to-Value (LTV) Work?
The core metric of any crypto loan is the Loan-to-Value (LTV) ratio. This ratio compares your borrowed amount against the market value of your deposited collateral.
Most industry LTV ratios range between 30% and 70%, with 50% being a standard starting point. At a 50% LTV, depositing $100,000 worth of Bitcoin allows you to borrow up to $50,000.
Margin Calls and Liquidation Risks
Because crypto asset prices fluctuate rapidly, market drops can push your LTV higher and increase risk.
Digital asset prices carry inherent volatility. Short-term market drops can trigger automated margin calls or collateral liquidations.
- Margin Call: If your LTV rises past a set safety threshold, the lender asks you to deposit more collateral or pay down part of the debt.
- Liquidation: If the price falls further and your LTV reaches a critical limit, the lender automatically sells your Bitcoin to cover the loan.
Understanding Rehypothecation
Rehypothecation occurs when a lender re-lends your collateral to third parties to generate extra yield. This practice contributed significantly to the bankruptcies of high-profile lenders like Celsius and BlockFi in 2022.
Modern lenders now frequently emphasize strict non-rehypothecation commitments or collaborative custody models to protect borrower funds.
Market Growth and Institutional Adoption
Following the failures of 2022, the crypto lending sector restructured around stronger risk management. According to Galaxy Research, centralized lending volume tripled from its late-2023 low point.
Total crypto loan volume stood at $56.16 billion in Q2 2026, dropping 16.8% from the previous quarter as market participants reduced overall leverage.
Traditional financial institutions have taken notice. In February 2026, Ledn closed a $188 million Bitcoin-backed asset-backed securitization. S&P Global assigned a preliminary 'BBB-' rating to its $160 million senior tranche.
Silicon Valley Bank (SVB) highlighted this as the first investment-grade rating awarded to a Bitcoin-collateralized lending portfolio. Additionally, Coinbase announced that its total Bitcoin loan originations surpassed $1 billion.
Leading Bitcoin Loan Providers
- Ledn: Focuses on custodied loans with a policy against re-lending borrower collateral.
- Unchained: Uses 2-of-3 multisig vaults where the borrower holds one key alongside Unchained and an independent agent.
- Strike: Provides Bitcoin-backed loans for consumers and businesses in select US states.
- Coinbase: Offers on-chain loans via the Morpho protocol across most US states.
- Aven: Launched a Bitcoin-backed Visa credit line in April 2026 featuring limits up to $1 million.
- Nexo: Supplies instant credit lines against BTC and over 100 assets, serving primarily non-US clients.
- Aave: A decentralized lending protocol that enables borrowing against wrapped BTC tokens.
Interest Rates and Borrowing Costs
Interest rates vary based on provider structure, LTV ratio, and loan size. Rates as of October 2026 reflect a distinct range across major platforms:
- Coinbase: Published interest rates start at around 5.8%.
- SALT: Advertises annual percentage rates (APR) from 7.49% to 10.5%.
- Ledn: Offers 11.49% APR on loans under $250,000, reducing to 9.25% for loans of $2 million or more.
- Strike: Charges between 10.5% and 13% APR for monthly payment plans, with an extra percentage point if interest is paid at maturity.
- Unchained: Quotes a 12% baseline interest rate, which translates to a 14.18% APR.
Beyond standard interest charges, borrowers should evaluate origination fees, prepayment penalties, and potential liquidation charges.
How to Get a Bitcoin-Backed Loan
- Select a Provider: Compare interest rates, custody setup, and non-rehypothecation policies.
- Complete Verification: Fulfill identity verification (KYC) requirements on centralized platforms.
- Choose LTV and Term: Select a conservative LTV ratio to provide a safety buffer against market pullbacks.
- Deposit Collateral: Transfer your Bitcoin to the platform's custodian, multisig vault, or smart contract.
- Receive Funds: Draw your loan in fiat currency or stablecoins.
- Monitor and Repay: Track your LTV ratio and make required payments to reclaim your collateral.
Regulations and Market Outlook
Regulatory frameworks surrounding crypto lending continue to evolve. Passing the GENIUS Act in the US helped clarify operational guidelines, though the broader CLARITY Act stalled in the Senate in September 2026.
SVB noted that multiple major financial institutions began launching Bitcoin-backed lending programs for institutional clients in early 2026.
Despite growing institutional involvement, fundamental risks remain. If Bitcoin's price drops sharply, over-leveraged borrowers face automatic liquidation.
DeFi lending also carries smart contract risks. In April 2026, an exploit linked to the Kelp DAO project drained $291 million, leading to $6.2 billion in capital outflows from Aave as users withdrew funds.
Borrowers should maintain conservative LTV ratios and understand where their private keys are stored.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Past performance of digital assets is not a guarantee of future performance.
Latest blog posts

XRP Ledger Proposes Quantum-Proof Security Upgrade
The XRP Ledger Foundation has proposed a zero-cost security upgrade designed to protect user accounts from potential future quantum computing threats.
|
HIVE Reports $78.7M Loss as AI Revenue Reaches $8.8M
HIVE Digital Technologies reported a quarterly net loss of $78.7 million on revenue of $84.9 million, alongside growth in its AI unit.
|
XRP Ledger Testnet and Devnet Set for November Reset
Ripple developers scheduled a full data reset for the XRP Ledger Testnet and Devnet on November 25, 2026, to improve node history server stability.
|